GCC and Jordan ESG disclosure
ESG disclosure in the GCC has moved from exchange guidance towards mandatory rules. Stock exchanges in the UAE, Saudi Arabia and Qatar publish ESG disclosure guidance for listed companies, Kuwait now requires Premier Market companies to publish a sustainability report under CMA Circular 04 of 2025, and regulators across the region are adopting the ISSB standards, IFRS S1 and IFRS S2. Jordan has made IFRS S2 mandatory for ASE20 companies from FY2026. Each market sets its own scope, timing and assurance expectations, so a group listed or operating in several of them has to track each one separately. This collection opens with a country-by-country summary, then covers ADX, DFM, Tadawul, Qatar, Kuwait and Bahrain in turn, followed by Jordan and its climate-first adoption of the ISSB standards. It closes with the choice of assurance standard and with what IFRS S2 does and does not require on transition plans.
14 articles, in reading order
-
ESG Disclosure Rules in the GCC, Country by Country
What each GCC state requires of listed companies and banks on ESG reporting, IFRS S1 and S2, assurance and climate risk, as at 18 October 2026.
Read insight → -
Demystifying ADX ESG Disclosure: Everything You Need to Know
An introduction to ADX ESG disclosure expectations, why listed issuers report ESG information and how organisations can prepare reliable disclosures.
Read insight → -
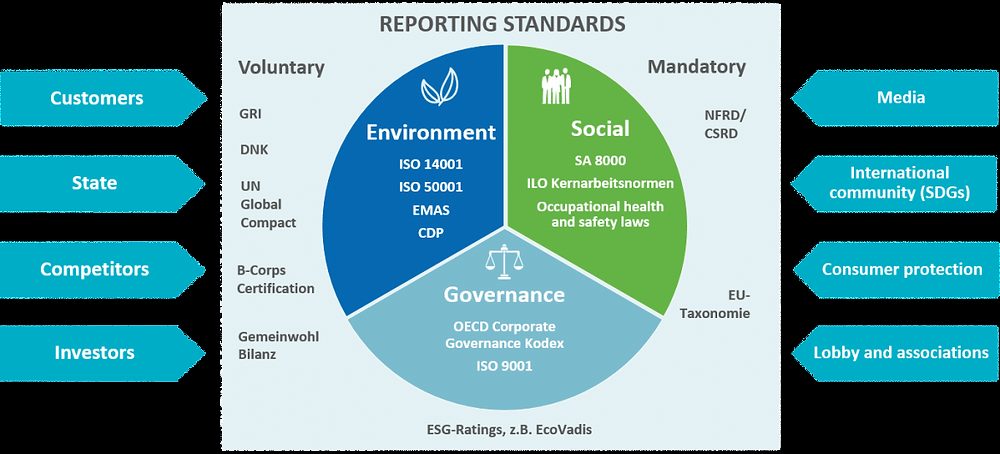
Dubai Financial Market (DFM) and ESG Reporting: A Comprehensive Overview
IntroductionThe Dubai Financial Market (DFM) has been at the forefront of promoting sustainability and responsible investment through its commitment to Environmental, Social,…
Read insight → -
Tadawul ESG Disclosure Guidelines: What Saudi-Listed Companies Need to Know
What the Saudi Exchange (Tadawul) ESG Disclosure Guidelines are, why ESG reporting in Saudi Arabia is still voluntary, and how listed companies prepare credible reports.
Read insight → -
ESG in Qatar: QSE Guidance, QFMA Governance, and What Listed Companies Should Do
How ESG reporting works in Qatar: the QFMA mandate for IFRS S1 and S2 on the Main Market, the voluntary QSE guidance, QCB and QFC rules, and what listed companies should do.
Read insight → -
IFRS S1 and S2 in Qatar: The ISSB Standards Reach the Gulf
IFRS S1 and S2 are mandatory in Qatar from FY2026 for Main Market listed companies, banks, insurers and QFC firms. What the standards require and how to prepare.
Read insight → -
QFMA Governance Code 2025 - Board Level Trainings View
IntroductionThe Qatar Financial Markets Authority (QFMA) has issued the Governance Code for Listed Companies 2025, a major update from the previous 2016 framework. Among the…
Read insight → -
Kuwait Makes ESG Reporting Mandatory: The 30 June 2026 Boursa Deadline
Boursa Kuwait Premier Market companies must publish a sustainability report under CMA Circular 04 of 2025, due by the end of Q2. Who is in scope and what is required.
Read insight → -
Bahrain's CBB ESG Requirements Module Explained
What the Central Bank of Bahrain ESG Requirements Module introduced, who it applies to, and how it positions Bahrain in the GCC's sustainable-finance landscape.
Read insight → -
Who Regulates Climate Disclosure in Jordan? Untangling CBJ, ASE and JSC
A clear map of who regulates climate and ESG disclosure in Jordan: the CBJ, the Amman Stock Exchange and the JSC, and why the binding climate text is ASE's.
Read insight → -
Jordan's Climate-First Adoption of ISSB Standards: A MENA Milestone
Jordan is confirmed by the IFRS Foundation as requiring ISSB sustainability disclosures, taking a climate-first path. Why it is a milestone for the MENA region.
Read insight → -
IFRS S2 Arrives in Jordan: What ASE20 Banks Must Disclose from FY2026
The ASE Climate-Related Disclosures Regulatory Framework makes IFRS S2 mandatory for ASE20 companies from FY2026. What Jordan's listed banks must disclose.
Read insight → -
ISO 14064-3 vs ISAE 3000 vs ISSA 5000: Which Assurance Standard?
How the main sustainability assurance standards differ, ISO 14064-3 for GHG, ISAE 3000 for non-financial information, and the new ISSA 5000, and when each applies.
Read insight → -
IFRS S2 Does Not Require You to Have a Transition Plan
IFRS S2 requires disclosure of a transition plan if one exists, at paragraph 14(a). It does not require an entity to have one. The distinction changes who the real driver is.
Read insight →


Other topics
- ISO management systems →
- UAE climate and environmental compliance →
- EU export rules: CBAM, methane and hydrogen →
- Net zero, SBTi and transition plans →
- Carbon markets and credits →
- Nature, biodiversity and Estidama →
- Sustainable finance instruments →
- Climate risk and banking regulation →
- ESG ratings, CSR and supply chains →